The world is currently grappling with a staggering global debt of $365 trillion, a figure that has reached an unprecedented level and is causing widespread economic concern. The escalating debt burden is not just a number—it translates into significant challenges for governments, businesses, and individuals worldwide, especially as interest payments on this debt continue to climb.
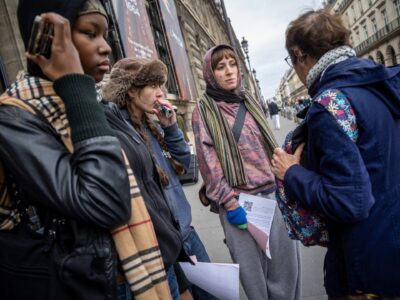
In Europe, the aftermath of the debt crisis is visibly manifesting through public protests and economic anxiety. Citizens across multiple countries are expressing their frustration as the cost of borrowing rises, putting pressure on national budgets and economic policies.
A particularly striking development has taken place in France, where the cost of borrowing has surged to an extent that the country now pays higher interest rates on its debt than Italy and even Greece. This is notable given the latter two countries’ well-documented struggles during the Eurozone debt crisis.
Analysts attribute this shift to multiple factors, including changes in investor confidence, domestic fiscal policies, and broader geopolitical risks. France’s increasing borrowing costs signify a renewed scrutiny by financial markets and signal potential difficulties for the country’s economic management.
The growing debt and rising interest rates pose a double-edged challenge. On one side, governments face the risk of hampered economic growth due to heavier debt servicing requirements that limit public spending capabilities in essential sectors such as healthcare, education, and infrastructure. On the other side, persistent high debt levels amplify vulnerability to financial shocks or economic downturns, potentially triggering more instability.
Globally, the $365 trillion debt reflects a complex interplay of factors, including pandemic-related spending, monetary policy responses, and structural economic issues. Many countries increased borrowing to support their economies during the COVID-19 crisis, leading to swelling national debts.
The situation is further complicated by the fact that interest rates, which have been relatively low in recent years, are now rising as central banks move to control inflation and stabilize economies. These rising rates translate into higher interest expenses on existing and new debts, thereby expanding the debt servicing burden.
European nations, in particular, are navigating a delicate balance. While increased borrowing costs constrain fiscal policy options, they also serve as a barometer of market confidence. High rates in France compared to Italy and Greece highlight shifting perceptions and new challenges within the Eurozone, suggesting that economic risks are evolving.
The public protests across Europe underscore the social implications of the debt crisis, with citizens concerned about austerity measures, cuts in social services, and the broader economic strain impacting their livelihoods.
Addressing this global debt dilemma requires coordinated international efforts that include prudent fiscal management, sustainable borrowing practices, and reforms aimed at stimulating economic growth while controlling debt accumulation.
In conclusion, the $365 trillion global debt and rising interest payments present a formidable challenge to economic stability worldwide. Europe’s recent experience, with France facing higher borrowing costs than Italy and Greece, serves as a critical example of the evolving debt landscape. Without effective measures, the economic and social consequences of this debt burden will likely intensify, affecting global financial systems and everyday lives.